
Executive Summary: A Democratic “blue wave” – control of both the House and Senate after the 3 November 2026 US midterms through the 2028 presidential election – would be a major political setback for President Trump but would not immediately end his policy programme, shifting the final two years from legislative execution toward executive action, litigation and political defense. Prediction markets point to a coinflip chance of this happening. For emerging markets, the theme matters less through US domestic politics than through three dominant external channels that drive EM returns: the US dollar, US real yields and the Treasury curve, and trade/tariff policy. The central thesis remains selective rather than outright negative, but the balance of risks is less supportive than current market pricing may imply. Constrained tariffs, lower front-end and intermediate US yields and a softer medium-term dollar could support EM local-currency debt, hard-currency sovereigns and trade-geared economies, provided US growth slows gently rather than abruptly. However, persistent political uncertainty, episodic risk-off shocks and a structurally elevated term premium are likely to cap upside and create a more volatile backdrop than in earlier easing cycles. The offset is that episodic risk-off from oversight, shutdown or constitutional-crisis headlines still triggers sharp, correlated EM drawdowns and spread widening, making this a high-dispersion credit landscape best expressed with quality and liquidity discipline.
Market Visualizer
A DEMOCRATIC BLUE WAVE: THE EM CREDIT READ-THROUGH
The Regime Shift: From Policy Execution to Policy Defense
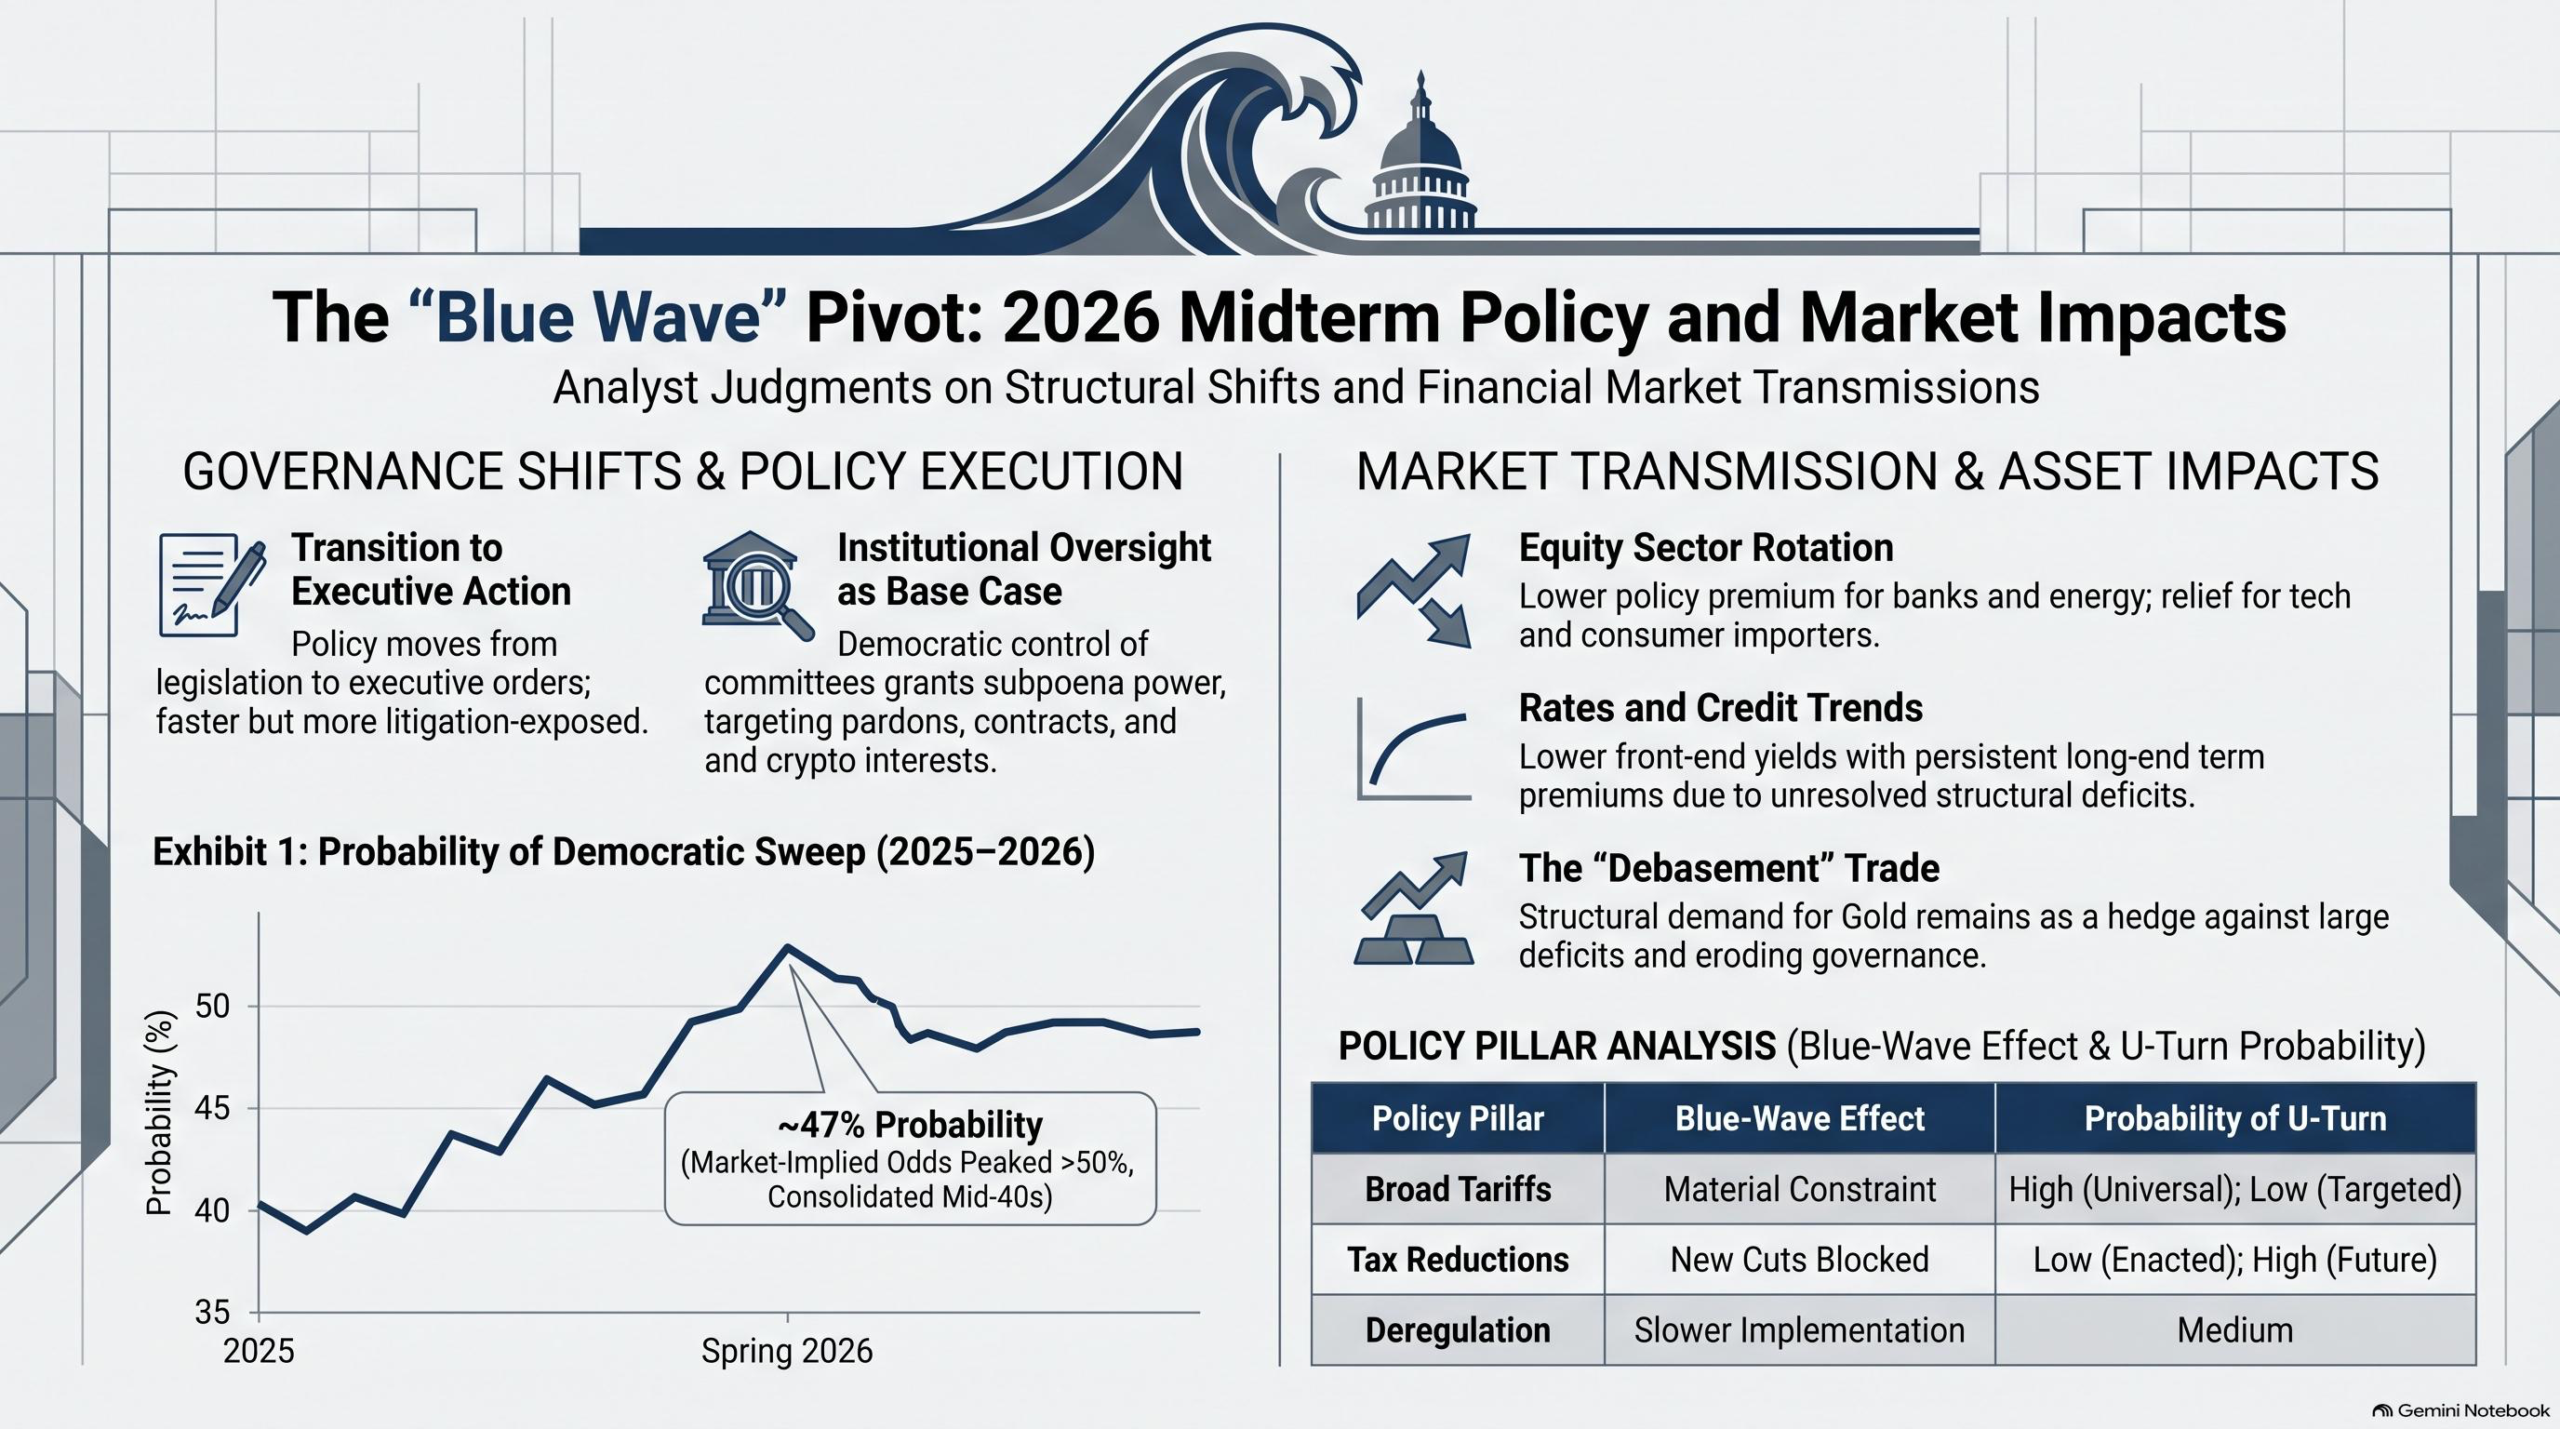
- Loss of the legislative machine: A full sweep hands Democrats committees, subpoenas, the legislative calendar, appropriations, agency oversight, Senate confirmations and the power to initiate impeachment – but not a veto-proof majority or the executive, so Trump remains president until January 2029 absent resignation, removal or incapacity. The mechanism is a pivot from durable legislation to reversible executive action, lowering the capitalised value of policy even when announced forcefully and increasing uncertainty around policy durability, investment decisions and corporate risk-taking.
- Executive action is fast but fragile: Orders and existing statutory authorities can be deployed quickly, but they are litigation-exposed and reversible; the February 2026 Supreme Court ruling that IEEPA does not authorize tariffs already forces reliance on the narrower, more procedural Sections 232 and 301, which require investigations and defined rationales.
- Durability discount: The new equilibrium is divided government with unusually intense institutional conflict – narrower, more legally contested and less durable policymaking – raising execution risk and the probability of selective U-turns, particularly where policies are economically costly, legally vulnerable or funding-dependent.
- Credit implication: A transition away from reflation and deregulation may support parts of investment-grade credit through lower rates, although any benefit could be moderated by slower growth, weaker confidence and elevated policy uncertainty, but more challenging for leveraged borrowers, private credit and policy-sensitive sectors, where lower policy durability and higher litigation risk widen risk premia.
Policy Pillars Under Constraint
- Tariffs – highest U-turn probability: With IEEPA rejected and reliance shifted to Sections 232/301, a Democratic Congress can hold cost-of-tariff hearings, restrict implementation appropriations and probe exemptions, raising the odds of a tactical U-turn from universal to targeted tariffs, quotas or bilateral deals. This lowers the probability of an unconstrained tariff-inflation shock, offering relative relief for retailers, consumer-goods importers, tech-hardware supply chains, import-dependent industrials, selected Asian and LatAm exporters, long-duration equities and intermediate Treasuries, although sector-specific disruption, policy reversals and trade uncertainty remain material risks.
- Tax – momentum freeze, not reversal: New broad-based cuts become highly unlikely and expiring provisions may lapse, but repeal over a veto needs two-thirds majorities (implausible), so the result is a freeze. Markets look to 2028, pricing higher corporate and high-income taxation, stronger minimum taxes, tighter carried-interest treatment and greater digital-asset taxation – a multiple-compression risk for banks, PE managers and domestically tax-sensitive names.
- Deregulation and immigration – slower, funding-constrained: Enforcement discretion continues, but Senate delay of nominees and committee oversight slow rulemaking and lower confidence that deregulation survives beyond 2028 (most exposed: banks/regional lenders, private credit/PE, fossil-fuel producers, tech platforms, contractors, crypto issuers, healthcare/pharma). Immigration authority survives, but appropriations can restrict detention capacity; quiet operational moderation is disinflationary for services and mildly supportive of potential growth.
- Fiscal – less expansion, more confrontation: The starting point is weak – CBO’s February 2026 baseline projected a $1.9tn FY2026 deficit (5.8% of GDP), with public debt rising from 101% of GDP in 2026 to 120% in 2036, and later tracking closer to $2.1tn. A sweep curbs unfunded stimulus but raises shutdown, delayed-appropriations and debt-ceiling risk, keeping a structural bid under the long-end term premium and real-asset hedges while increasing the potential for periodic volatility linked to fiscal confrontation and budget negotiations.
Policy Execution Matrix
| Trump policy pillar | Blue-wave effect | Probability of U-turn | Primary market transmission |
|---|---|---|---|
| Broad tariffs | Material constraint | High for universal tariffs; lower for targeted tariffs | Lower goods inflation; weaker USD; relief for importers |
| Tax reductions | New cuts blocked | Low for enacted measures; high for future proposals | Less earnings upside; modestly lower deficits |
| Deregulation | Slower but not fully reversed | Medium | Pressure on banks, energy and private capital |
| Immigration restrictions | Continues through executive authority, but funding constrained | Medium | Labor supply, wages and services inflation |
| Fiscal expansion | New initiatives constrained; shutdown risk rises | Medium | Lower near-term growth, persistent term premium |
| Energy dominance | Legislative expansion blocked; permits and enforcement continue | Low-to-medium | Higher policy risk for oil and gas |
| Foreign policy and sanctions | Executive retains substantial authority | Low | Continued geopolitical and commodity volatility |
| Crypto liberalization | Greater oversight and legislative resistance | Medium-to-high | Negative for speculative tokens and crypto intermediaries |
Oversight, Impeachment Risk and the Response Function
- Oversight is the base case: A Democratic House gains subpoena, hearing and investigation powers reportedly targeting self-dealing, foreign influence, contracts, pardons and crypto interests – impairing governing capacity even without impeachment by consuming bandwidth, deterring counterparties and prompting resignations. Markets respond to impairment of execution, not merely legal entitlement to office, particularly when prolonged investigations create uncertainty around fiscal negotiations, regulatory implementation and policy continuity.
- The arithmetic of removal: Impeachment needs only a simple House majority (moderate probability), but conviction requires two-thirds of the Senate (low). The probability ladder below ranks extensive investigations “very high,” a Judiciary inquiry “moderate-to-high,” and conviction/removal and resignation “low”/”very low” – so policy paralysis without removal (“high”) is the most market-relevant outcome.
- Trump’s three response paths: Confrontation (resist subpoenas, litigate, weaponise shutdown fights) is most disruptive – higher volatility, demand for cash/USD/Treasuries, wider spreads, stronger gold, mixed Bitcoin. Selective accommodation (negotiate budgets, infrastructure, industrial policy) is most market-friendly. A tactical U-turn recalibrates the costliest, legally weakest policies, presented as success rather than reversal.
- Asymmetry for credit: The higher the congressional and judicial constraint, the greater the odds Trump substitutes symbolic confrontation for economically costly implementation – a channel through which risk assets can rally even as rhetoric hardens, while evidence peeling away Republican senators or forcing senior resignations is the true tail-risk trigger for spread widening.
Probability Ladder
| Event | Qualitative probability after blue wave | Assessment |
|---|---|---|
| Extensive investigations | Very high | Central Democratic strategy |
| Judiciary Committee inquiry | Moderate-to-high | Depends on evidence and leadership strategy |
| House impeachment | Moderate | Simple majority is sufficient |
| Senate trial | High if House impeaches | Follows transmission of articles, subject to procedure |
| Senate conviction and removal | Low | Requires substantial Republican support |
| Trump resignation | Very low | Would require severe legal or political isolation |
| Policy paralysis without removal | High | Most plausible market-relevant outcome |
Rates, the Dollar and the Debasement Regime
- Cyclical inflation trade weakens: As of the July 2026 Monetary Policy Report, headline PCE reached 4.1% y/y in May and core PCE 3.4%, with tariffs and the Middle East energy shock adding pressure and minutes flagging possible further tightening. A sweep that constrains additional tariffs and tax cuts lowers medium-term inflation expectations and creates room for eventual easing if growth weakens, although markets may increasingly interpret future rate cuts as a response to deteriorating growth conditions rather than a clean inflation victory.
- Structural debasement trade persists: With mandatory spending and interest costs driving the deficit regardless of party, there is no decisive end to the US debasement narrative, keeping a structural bid under the long-end term premium; the net is lower 2-10y yields with a re-steepening long end.
- Curve and credit positioning: Favor lower 2y/5y/10y yields and eventual 10s30s steepening – preferring 5-10y duration over an outright 30y long. IG should remain relatively resilient as rates decline, although lower yields alone may not prevent wider risk premia if growth disappoints or fiscal confrontations intensify; HY is mixed, with a preferred order of intermediate IG, strong BB, defensive EM duration, select bank senior, then loans/private credit only with strong coverage.
- FX and real assets: The USD firms briefly on risk aversion then weakens as gridlock slows growth and eases policy; gold remains the cleanest debasement hedge, Bitcoin sees an initial regulatory sell-off then recovery if debasement persists, while altcoins/DeFi are most vulnerable to tighter enforcement.
Emerging Markets: Transmission, Winners and Losers
-
- The dollar is the dominant signal: An initial safe-haven bid could briefly tighten EM financial conditions, but the more durable move – a softer dollar on slower US growth, constrained tariffs and eventual Fed easing – has historically been supportive for EM, easing financial conditions, supporting local FX and lowering hard-currency debt-service burdens, although the benefit could prove smaller than in prior cycles if dollar weakness is driven primarily by slowing US growth rather than improving global risk appetite.
- Real yields and the curve: Lower 2-10y US yields and reduced breakevens compress the risk-free component of EM hard-currency spreads and improve refinancing math for well-run sovereigns and quasi-sovereigns, though tighter financial conditions and weaker growth could still offset part of that benefit; the caveat is a persistent long-end term premium that caps how far EM long duration can rally and leaves EM exposed to any disorderly 30-year Treasury sell-off.
- Trade and tariffs: A shift from universal to targeted, negotiated measures reduces the tariff-inflation shock and creates clearer bilateral frameworks that offer relative support to open, export-geared EMs and manufacturing supply-chain hubs, although softer global demand may limit those gains; commodity exporters remain exposed to a growth setback, while importers benefit only if tariff-driven price pressure fades.
The Three Transmission Channels
| Channel | Blue-wave effect | EM transmission |
|---|---|---|
| US dollar | Brief risk-off strength, then medium-term softening on slower growth and eventual Fed easing | A weaker USD eases EM financial conditions, supports local FX, lowers hard-currency debt-service burdens and typically drives EM inflows |
| US real yields & curve | Lower 2-10y yields and reduced breakevens; long-end term premium persists | Lower front-end/belly yields improve EM carry and duration; a steep long end keeps the tail risk of a disorderly UST sell-off spilling into EM |
| Tariffs & trade | Universal tariffs constrained; shift to targeted, negotiated measures | Reduced tariff-inflation shock and clearer bilateral frameworks benefit open, export-geared EMs and manufacturing supply-chain hubs |
| Commodities | Continued geopolitical/sanctions volatility; energy price risk two-sided | Commodity exporters gain on firm energy/metals; importers benefit if tariff-driven price pressure fades |
| Risk sentiment | Higher US political-headline volatility (oversight, shutdown, crisis tail) | Episodic correlated risk-off, spread widening and outflows – a discipline constraint, not a reason to be structurally short EM |
EM Winners and Losers
| EM segment | Bias | Rationale |
|---|---|---|
| Trade-geared Asian & LatAm exporters | Winner | Tariff de-escalation and clearer bilateral frameworks; supply-chain relocation beneficiaries |
| High-real-yield local-currency markets (credible central banks) | Winner | Softer USD and US disinflation create room to ease; attractive carry with FX tailwind |
| IG & strong-BB EM sovereigns / quasi-sovereigns | Winner | Lower front-end/belly US yields compress spreads and ease refinancing |
| Commodity exporters (energy & metals) | Mixed | Gain from firm commodity prices and geopolitics; exposed if global growth slows sharply |
| Weak-external-balance, high-refinancing-need frontier credits | Loser | Most exposed to risk-off episodes, wider spreads and a disorderly long-end UST sell-off |
| Heavily commodity-import-dependent economies | Loser | Vulnerable if energy/food prices stay high; thinner buffers against external shocks |
Scenario Analysis
| Scenario | Probability bias | Trump execution capacity | Market regime |
|---|---|---|---|
| Democratic House; Republican Senate | Most plausible | Legislation blocked; executive action remains strong; investigations intensify | Gridlock, moderate volatility, duration-positive |
| Full blue wave; no impeachment | Meaningful alternative | Confirmations and legislation constrained; heavy oversight | Lower yields and a softer USD, though accompanied by weaker growth expectations and elevated political uncertainty |
| Blue wave plus House impeachment | Tail but credible | Severe political distraction; executive actions continue | Risk-off initially; gold and Treasuries outperform |
| Impeachment plus credible Senate conviction risk | Low-probability tail | Administration potentially paralyzed | Sharp volatility, credit widening, USD path ambiguous |
| Blue wave prompts Trump moderation | Underpriced upside | More negotiated and targeted policy | Bullish equities and credit; bearish inflation premium |
| Confrontation and constitutional crisis | Low-frequency, high-impact | Execution shifts to courts and emergency authority | Gold up, risk assets down, long-end Treasury volatility |
Credit / Investment Implications
The blue-wave shock works by substituting durable legislation for reversible executive action under intensifying oversight, lowering the policy premium while leaving the structural fiscal-debasement problem unresolved. The impact is asymmetric: cyclical inflation and tariff risk fall (bullish the front end, IG and EM carry), but the long-end term premium is sticky and headline-driven risk-off can widen spreads regardless of fundamentals – so weak frontier and leveraged credit are the most exposed segments, making this a selective rather than outright constructive backdrop for EM. Opportunities remain in higher-quality credits and stronger sovereign balance sheets, but discipline, liquidity management and issuer selection are likely to matter more than broad beta exposure.
www.gembridgecapital.com
DISCLAIMER
This document is strictly confidential and is being provided to you for informational purposes only. It does not constitute an offer to sell or a solicitation of an offer to buy any securities or financial instruments. The information contained herein has been obtained from sources believed to be reliable but is not guaranteed as to accuracy or completeness. Opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice.
AI Generation Notice: Portions of this content may have been generated or assisted by Artificial Intelligence (AI) technologies. Users should independently verify critical data points. Past performance is not indicative of future results.