
GEMBRIDGE CAPITAL
Global Emerging Markets Credit Strategy
Week Ending: August 28, 2026
Key Takeaways
- EM bond funds absorbed US$1.1 billion, the strongest weekly intake in 12 weeks, with both hard-currency and local-currency funds attracting money and YTD inflows reaching US$33.9 billion.
- Hawkish central-bank commentary at Jackson Hole lifted the perceived probability of a September Fed hike from 36% to 60%, raising the risk that Treasury volatility offsets otherwise-supportive EM technicals.
- Sovereign credit outperformed corporates across every reported ex-Asia region, led by Latin America at +0.63%, while corporate returns compressed into a 0.17–0.23% band.
- Colombia was the week’s clearest volatility event as a revised 2027 budget revealed a 9.4%-of-GDP deficit, leaving CDS 8bp wider even as cash bonds retraced to roughly unchanged.
- September supply is the central technical risk, with roughly US$90 billion of further EM sovereign issuance forecast for the remainder of 2026 competing against heavy global IG demand.
Market Visualizer
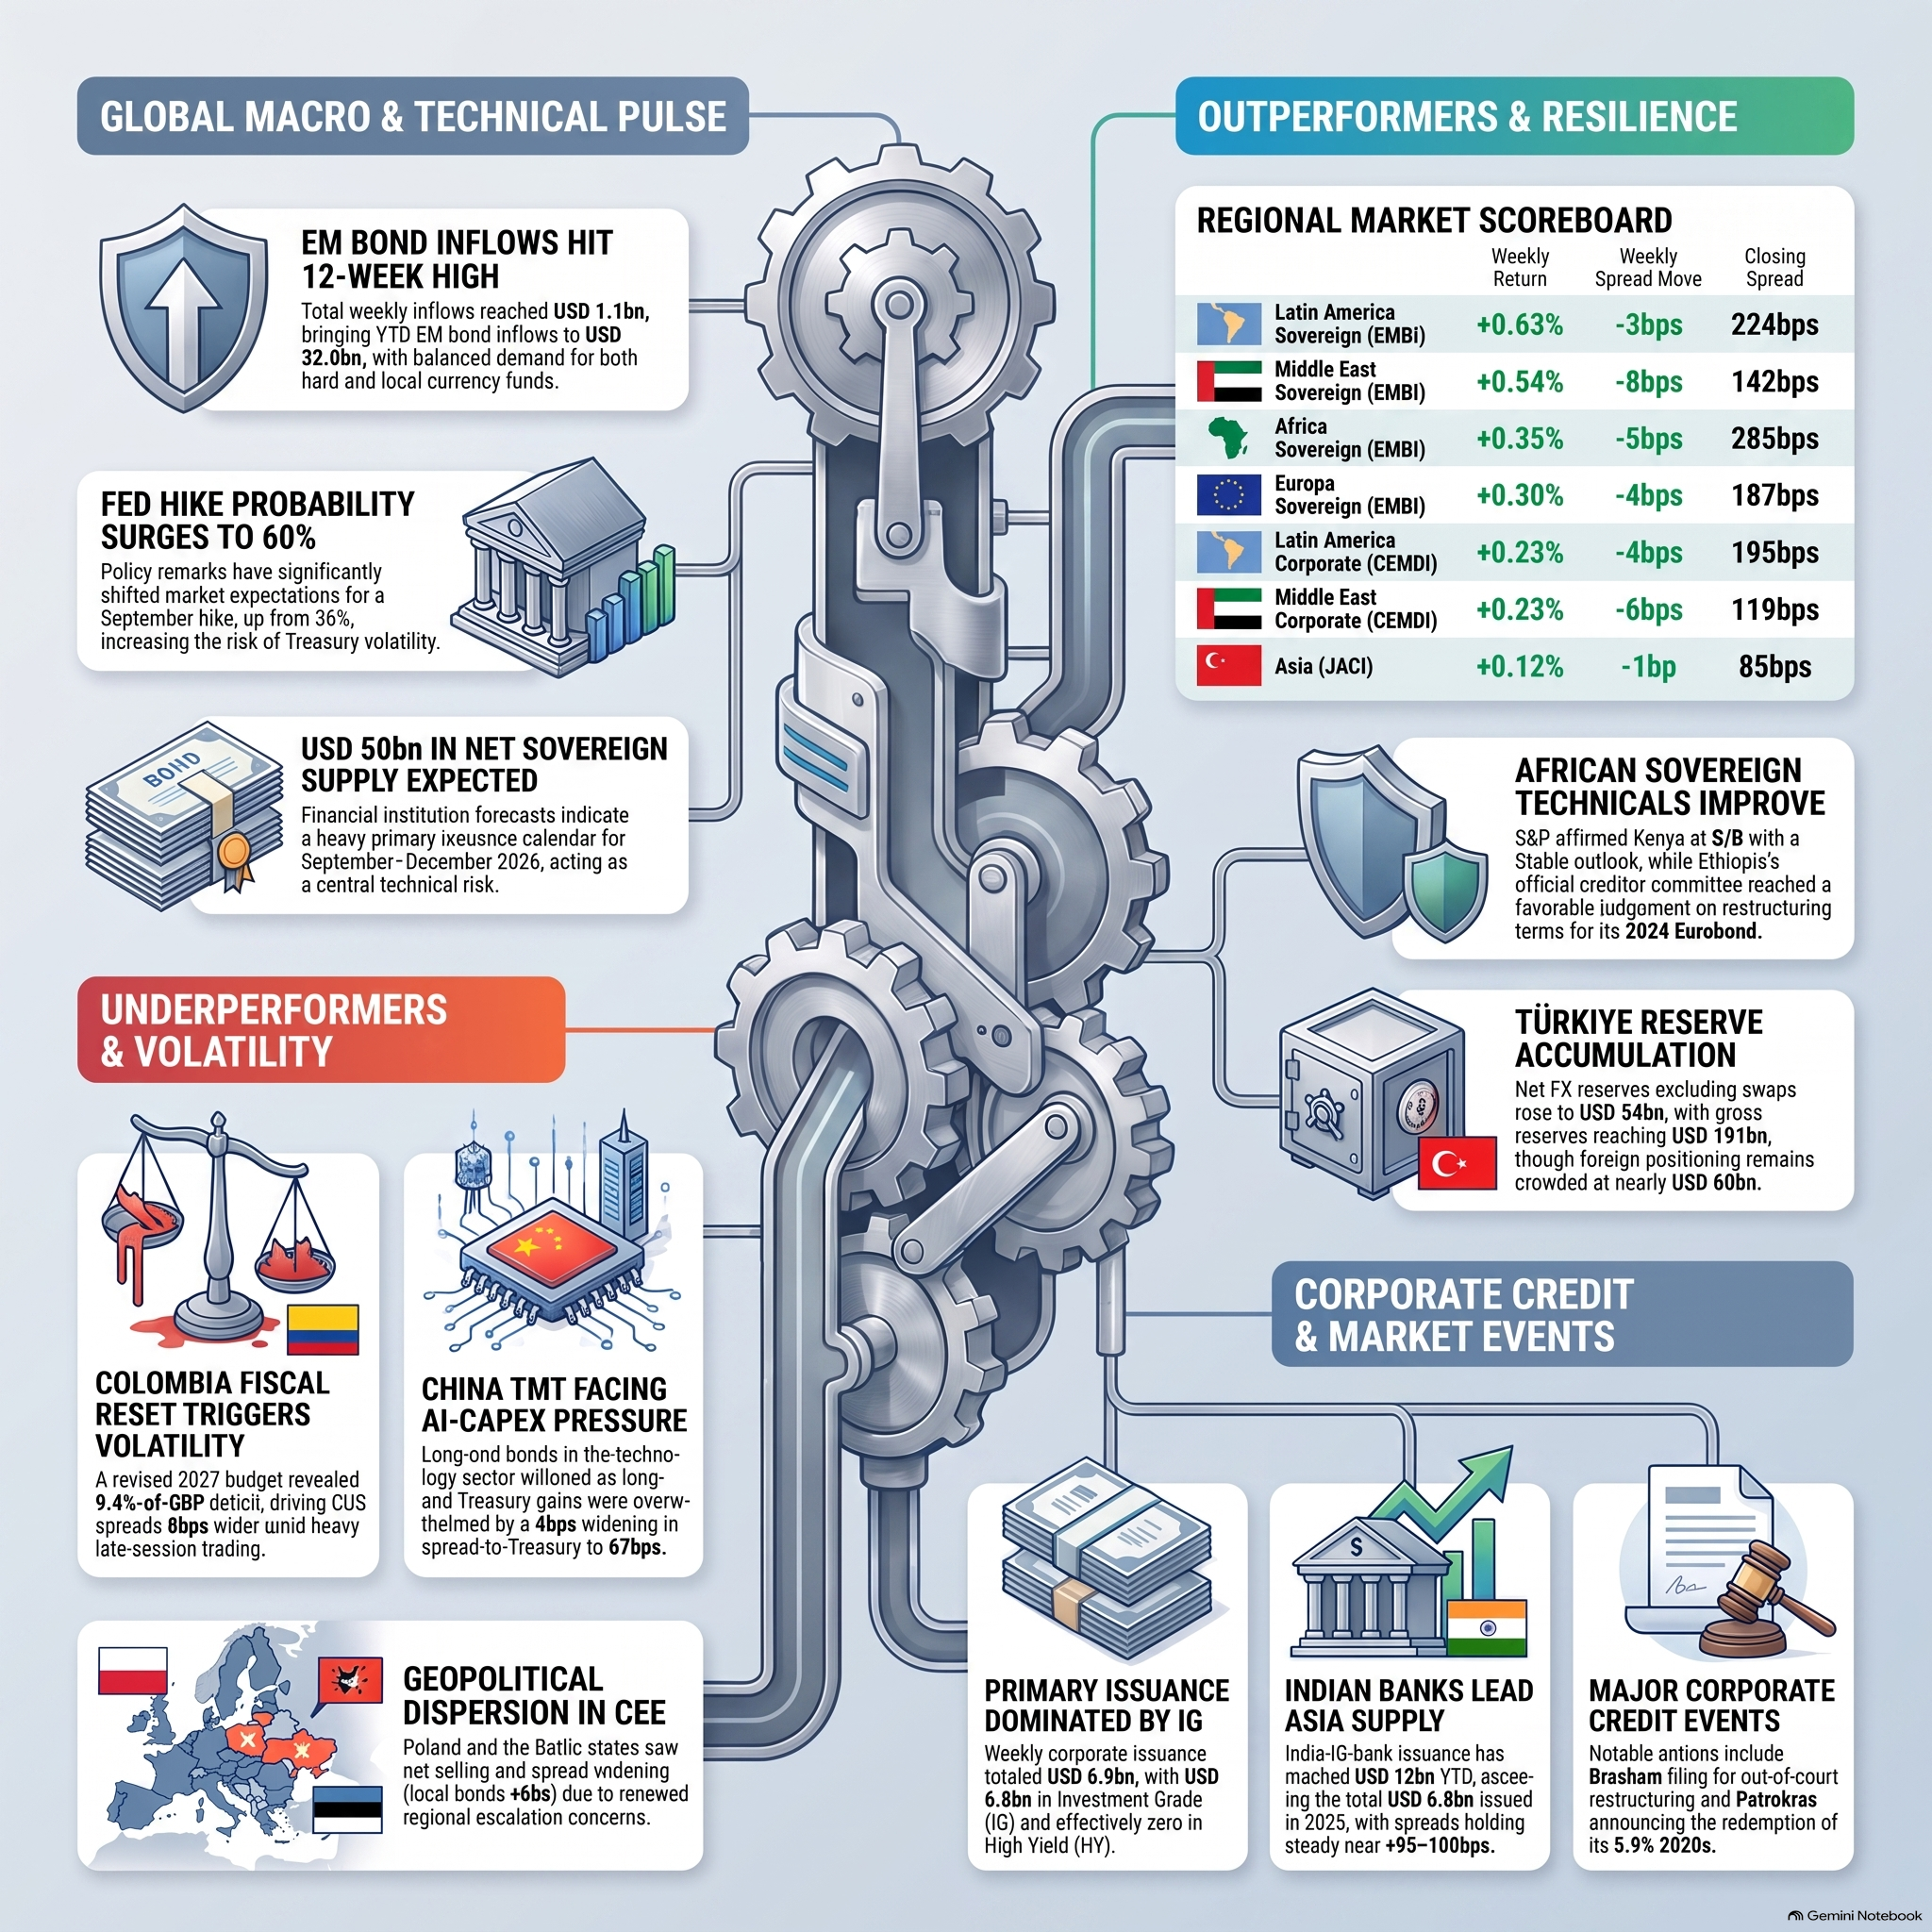
Weekly Snapshot: Key Drivers & Regional Flows
Regional Credit Developments
Global EM Themes
Flows & Technicals
- EM bond inflows rose to US$1.1 billion, split US$584 million into hard currency and US$516 million into local currency; ETFs contributed US$519 million and non-ETFs US$581 million, taking YTD EM bond inflows to US$33.9 billion.
- Broad hard-currency EM funds attracted US$598 million, while Asia ex-Japan hard-currency funds lost US$14 million.
- Local-bond inflows were geographically concentrated, with Hungary leading available non-resident inflows at US$92 million; in Asia dollar corporates a modest buying bias and rotation toward bonds longer than ten years saw China reverse to a 14% net inflow while Hong Kong, India and Singapore recorded net outflows.
- Sovereigns outperformed corporates across every reported ex-Asia region, with Latin America sovereign +0.63% (-3bp to 224bp), Middle East +0.54% (-8bp to 142bp), Africa +0.35% (-5bp to 285bp) and Europe +0.30% (-4bp to 187bp) against compressed corporate returns of 0.17–0.23%.
Macro & Economics
- Hawkish Jackson Hole remarks lifted the perceived probability of a September Fed hike from 36% to 60%, increasing the risk that Treasury volatility overwhelms supportive EM technicals.
- Mexico’s 2026 growth forecast was raised to 1.5% on firm external demand and industrial-policy traction, while Brazil is expected to slow from 4.5% annualized in 1Q to 2% in 2Q and toward 1% in early 3Q on high debt-service costs and a fading fiscal impulse.
- Policy divergence widened, with five of seven EMEA EM central banks expected to cut — Türkiye effectively lowered interbank funding rates by 300bp and is forecast to cut 100bp in both October and December, and Hungary is seen cutting 25bp in September — while Asia turned more hawkish as Korea and the Philippines raised rates and Thailand held on weak, uneven growth.
Regional Developments
Middle East & Africa
- MENA stayed range-bound despite renewed US-Iran tension; GCC IG was slightly softer in cash with no broad spread pressure, while higher oil supported exporters and wider bid-offer spreads reflected a geopolitical premium amid an empty near-term pipeline.
- Bahrain’s 2033 sukuk tightened about 10bp in z-spread and its 2028 and 2038 conventional bonds tightened roughly 20–25bp, while Oman’s January 2028 bond outperformed the October 2027 point by around 25bp on thin liquidity.
- Over five sessions the high-grade, high-beta, HY and AT1 baskets tightened 1.6bp, 8.1bp, 2.2bp and 5.6bp respectively, with MENA HY range-bound and AT1s broadly unchanged to slightly lower.
- African sovereign technicals improved, with duration extension in Angola, better belly buying in Kenya, two-way flow in Nigeria and a South African curve 1–3bp tighter alongside CDS 0.5bp tighter.
- Kenya was affirmed at B/B with a Stable outlook on stronger reserves and exchange-rate stability, while Ethiopia’s official creditor committee judged the restructuring terms for its US$1 billion 2024 Eurobond compliant with comparability-of-treatment requirements.
- Cameroon’s 2033 bond gained 0.32 cents to 98.51 as its yield fell to 9.18% after the president returned from a prolonged absence, and Ghana’s banking-system capital ratio rose to 20.4% in June from 10.6% a year earlier, with all 23 banks fully capitalized.
Eastern Europe (CEE)
- Ukraine traded down 0.25 points before finishing 0.125 points higher amid balanced activity.
- Poland was the principal weak point on renewed Russian-escalation concerns, with hard-currency bonds widening roughly 1–2bp and local bonds about 6bp, while Latvia and Lithuania also saw net selling.
- Türkiye’s foreign carry exposure fell US$1.2 billion over two weeks to US$48.7 billion, still well above the roughly US$40 billion pre-conflict level, with short-term foreign positioning near US$60 billion including money-market funds; net FX reserves excluding swaps rose to about US$54 billion and gross reserves reached US$191 billion.
Latin America
- Colombia’s revised 2027 budget revealed a 9.4%-of-GDP deficit and a planned 2.2 percentage-point primary adjustment; cash traded 4–6bp wider and CDS as much as 6bp wider before cash retraced to roughly unchanged, though CDS closed 8bp wider with more than US$200 million traded in the final hour.
- Argentina stabilized after meaningful underperformance as passage of central-bank charter reform and the Fiscal Innocence bill through the Lower House triggered a 25–50 cent opening rally and a curve close about 20 cents higher, leaving bonds still down roughly 4 points and 100bp wider month-to-date.
- Braskem filed for an out-of-court restructuring; Fitch upgraded Brava Energia to BB from BB- following Ecopetrol’s acquisition of control; Fitch removed Rumo from Rating Watch Negative but assigned a negative outlook; and Petrobras announced redemption of its 5.9% 2028 notes.
Asia
- JACI gained 0.12%, with sovereigns returning 0.29%, quasis 0.13% and corporates 0.06%, and Pakistan led country returns at 0.58%.
- China IG lost 0.03% as a 4bp widening in spread-to-Treasury to 67bp overwhelmed seven-year Treasury gains, with technology long-end bonds widening on concerns over the size and duration of AI capex and reported hedge-fund shorting on prospective supply and sanctions risk.
- China financial spreads widened 5bp versus only 1bp for Asia financials overall, while Asia gaming returned 0.17% with spreads tightening 4bp to SOT+188 across both IG and HY.
- SoftBank hybrid bonds fell as much as 2.5 points after potential US$10–20 billion refinancing headlines.
Primary Markets
- Through August 27, EM corporate issuance totaled US$6.9 billion WTD, of which US$6.8 billion was IG and effectively zero was HY; Asia supplied US$4.9 billion, Emerging Europe US$1.1 billion, Middle East and Africa US$0.9 billion and Latin America none, taking YTD corporate issuance to US$357.1 billion.
- Approximately US$12 billion of India IG-bank supply already exceeded the roughly US$6.5 billion issued in all of 2025, yet most deals performed and high-quality five-year bank spreads held near +95–100bp, while the broader Asia primary market raised US$2.4 billion entirely in IG.
- September supply is the central technical risk, with roughly US$90 billion of further EM sovereign USD/EUR issuance forecast for 2026 and US$50 billion of net issuance during September–December, historically led by EEMEA and competing with heavy US hyperscaler financing for global IG demand.
GEMBRIDGE CAPITAL
www.gembridgecapital.com
www.gembridgecapital.com
DISCLAIMER
This document is strictly confidential and is being provided to you for informational purposes only. It does not constitute an offer to sell or a solicitation of an offer to buy any securities or financial instruments. The information contained herein has been obtained from sources believed to be reliable but is not guaranteed as to accuracy or completeness. Opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice.
AI Generation Notice: Portions of this content may have been generated or assisted by Artificial Intelligence (AI) technologies. Users should independently verify critical data points. Past performance is not indicative of future results.
© 2026 Gembridge Capital. All rights reserved.