
GEMBRIDGE CAPITAL
Global Emerging Markets Credit Strategy
Week Ending: 3 October 2026
Key Takeaways
- EM fixed income weakened across the principal asset classes, with hard-currency sovereigns returning -1.59%, local-currency debt -1.11% and EM corporates -0.83% at the 2 October mid-day cut-off.
- Long-duration and lower-quality sovereign credit underperformed as 10-year-plus bonds returned -2.66% and HY sovereigns returned -1.86%, versus -0.45% for the 1–3-year segment and -1.29% for IG.
- Dedicated hard-currency EM debt funds recorded US$789m of net outflows, while China-focused and regional local-currency vehicles continued to attract inflows.
- Credit risk widened unevenly, with CDX EM moving 14.9bp wider to 166bp while iTraxx Asia ex-Japan IG widened only 0.6bp to 70bp.
- Primary issuance slowed to US$8.5bn under the broader reported universe, while higher Treasury yields contributed to a postponed benchmark transaction.
Market Visualizer
Weekly Snapshot: Key Drivers & Regional Flows
Global EM Themes
Flows & Technicals
- Global-mandated EM debt funds recorded US$909m of outflows, including US$878m from hard-currency mandates and US$117m from local-currency mandates.
- Regional and country local-currency funds attracted US$3.0bn, including US$3.5bn of ETF inflows, although both figures slowed from US$4.9bn and US$5.9bn previously.
- Hard-currency sovereign returns were -2.27% in Africa, -1.72% in Europe and -0.98% in Asia, while corporate returns ranged from -1.48% in Latin America to -0.28% in Asia.
- Brent hovered around elevated levels of US$100/bbl.
Macro & Economics
- DM front-end yields rallied 10–30bp while curves steepened approximately 10–20bp, leaving long-duration EM bonds particularly exposed despite the front-end rally.
- September US payroll growth was 29k, prior months were revised down by 60k and unemployment stood at 4.2%, reducing the market-implied probability of an October Fed hike from about 70% to 20%.
- Macro readings were mixed across Asia, with India’s manufacturing PMI rising to 55.1, South Korean CPI easing to 2.9% y/y and Indonesian CPI increasing to 3.28%.
Regional Developments
Middle East & Africa
- MENA high-grade credit widened 22bp over five sessions, while high-beta sovereigns widened 38bp, HY corporates 47bp and AT1/perpetuals 29bp.
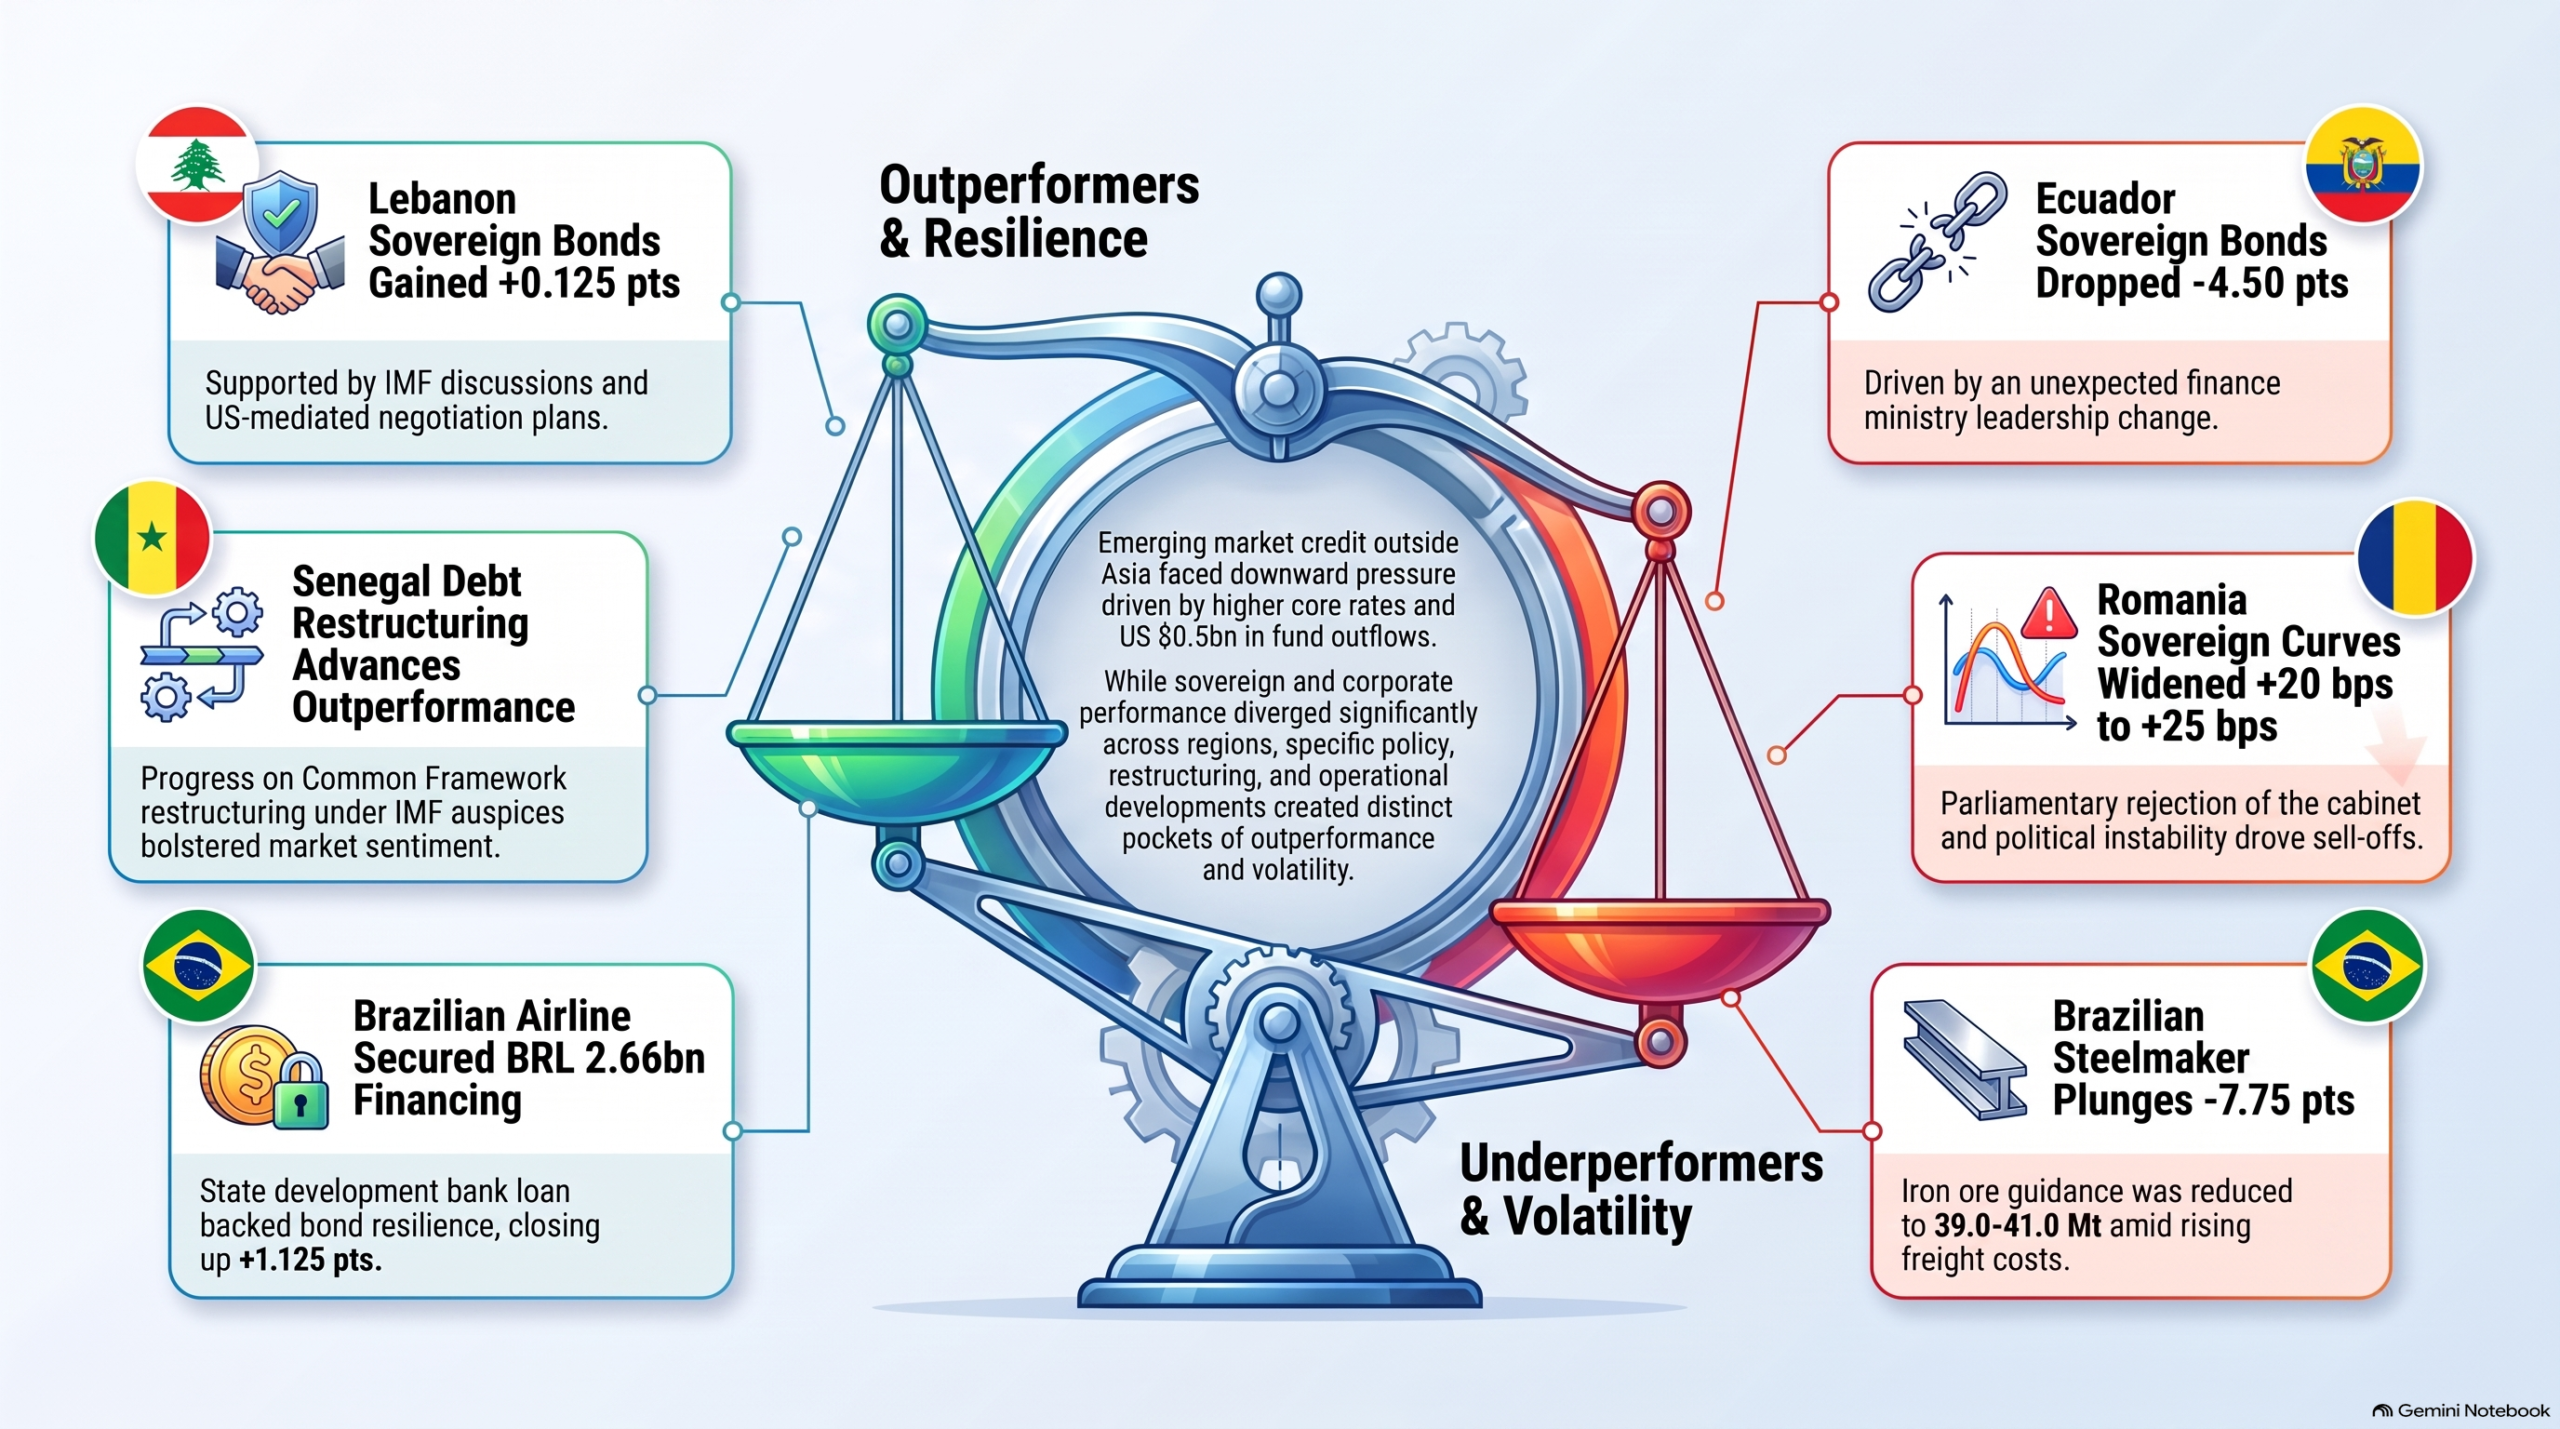
- Long-duration Bahrain, Egypt and Jordan sovereign bonds lost 2.5 pts, 4.5 pts and 4.3 pts, respectively, while a short-dated Oman bond gained 0.75 pt.
- Senegal scheduled an IMF-chaired creditor meeting for 6 October covering its economic programme, debt-treatment strategy and engagement timetable, while reiterating that domestic debt remained outside the intended treatment perimeter.
- Angola’s sovereign outlook was revised to positive with its B3 rating affirmed, while projected government debt and interest costs stood at approximately 46% of GDP and 23% of revenue by end-2026.
- South Africa’s first-five-month FY26 deficit narrowed to R188.8bn from R215.2bn as revenue rose 9.5% and expenditure increased 4.6%, although local-market debt returned -2.41% during the week.
- Zambia cut its policy rate by 250bp to 10.75% after inflation eased to 6.1% and opened discussions with the IMF on a successor ECF programme.
Eastern Europe (CEE)
- Romania’s 2026 gross financing needs were estimated at RON278.5bn, including a 6.2%-of-GDP deficit and RON150.7bn of maturities, with issuance through end-September covering approximately 52.2% of the requirement before other funding sources.
- Romania’s government-formation uncertainty remained a credit focus after Parliament rejected the proposed government, while local-currency debt returned -2.17%, predominantly through FX.
- Polish headline inflation rose to 4.0% y/y, above the 3.5% upper tolerance limit, although estimated core inflation eased to 3.2% from 3.3%.
- Ukraine recorded a -5.26% weekly hard-currency sovereign return, the second-weakest country performance in the reported sovereign universe.
Latin America
- Brazil entered the 4 October first-round presidential vote with a statistically tight race, while five-year CDS widened 7bp to 130bp and August unemployment remained at 5.3%.
- Colombia raised its overnight lending rate by 25bp to 12.25% following higher inflation, while five-year CDS widened 14bp to 177bp.
- Chile’s August activity contracted 1.0% y/y and 0.7% m/m as mining fell 10.7% m/m, while five-year CDS widened 8bp to 59bp.
- Mexico maintained its policy rate at 6.50%, with the central bank citing domestic slack and the inflation outlook, while five-year CDS widened 12bp to 101bp.
- Stress intensified in a major Brazilian industrial credit CSN as its 2030 bond fell 8pts to $71, yielding 22.7%, after lower-grade production and cost guidance deteriorated.
Asia
- China, Indonesia and Philippines five-year CDS widened 2bp, 4bp and 4bp, respectively, even as the broader regional IG index widened only 0.6bp to 70bp.
- Long-dated Indonesia and Philippines sovereign bonds fell 0.25–0.50 pt early in the week, while Sri Lanka lost 0.5 pt and Pakistan declined a further 0.25–0.50 pt amid selling and thinner bid-side liquidity.
- Corporate performance remained highly dispersed, with several Kazakhstan and Türkiye credits losing 4–5 pts while selected China and Japan-related bonds gained 1 pt.
Primary Markets
- EM credit issuance totaled US$8.5bn, down from US$14.0bn previously, including US$5.5bn of sovereign supply and US$3.5bn of ESG-labelled issuance.
- A narrower external hard-currency universe recorded approximately US$7.1bn across six issuers and nine tranches; differing universes and cut-offs prevent direct reconciliation with the US$8.5bn broader tally.
- A planned benchmark, Marfrig 7/10-year corporate transaction was postponed after higher Treasury yields increased expected borrowing costs, with proceeds originally intended partly to refinance US$467m of 2029 notes.
- Liability-management activity included the announced redemption at par of US$235m of Adecoagro’s 2027 notes and a BRL2.6bn five-year development-bank facility, of which BRL1.3bn had been drawn.
- Ghana’s B-/B sovereign ratings were affirmed with a stable outlook alongside a planned GHS78bn central-bank recapitalisation, while Angola’s B3 rating was affirmed with a positive outlook.
GEMBRIDGE CAPITAL
www.gembridgecapital.com
www.gembridgecapital.com
DISCLAIMER
This document is strictly confidential and is being provided to you for informational purposes only. It does not constitute an offer to sell or a solicitation of an offer to buy any securities or financial instruments. The information contained herein has been obtained from sources believed to be reliable but is not guaranteed as to accuracy or completeness. Opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice.
AI Generation Notice: Portions of this content may have been generated or assisted by Artificial Intelligence (AI) technologies. Users should independently verify critical data points. Past performance is not indicative of future results.
© 2026 Gembridge Capital. All rights reserved.