
GEMBRIDGE CAPITAL
Global Emerging Markets Credit Strategy
Week Ending: 9 October 2026
Key Takeaways
- EM credit sentiment improved into week-end as sovereign spreads tightened across parts of Latin America and CEEMEA, while Asia credit remained broadly defensive amid continued de-risking.
- Romania, Turkey, Ukraine and Kyrgyzstan outperformed following supportive political, macroeconomic and rating developments, driving meaningful spread compression and cash price gains.
- Asia high-yield corporates underperformed with continued pressure across transportation, gaming and property credits, although selected China industrial names diverged sharply.
- Primary market activity remained constructive as Laos successfully placed a US$500 million sovereign issue with strong demand and secondary market performance.
- Flows stabilized across EM credit after recent volatility, with investors selectively adding exposure to higher-yielding sovereign opportunities.
Market Visualizer
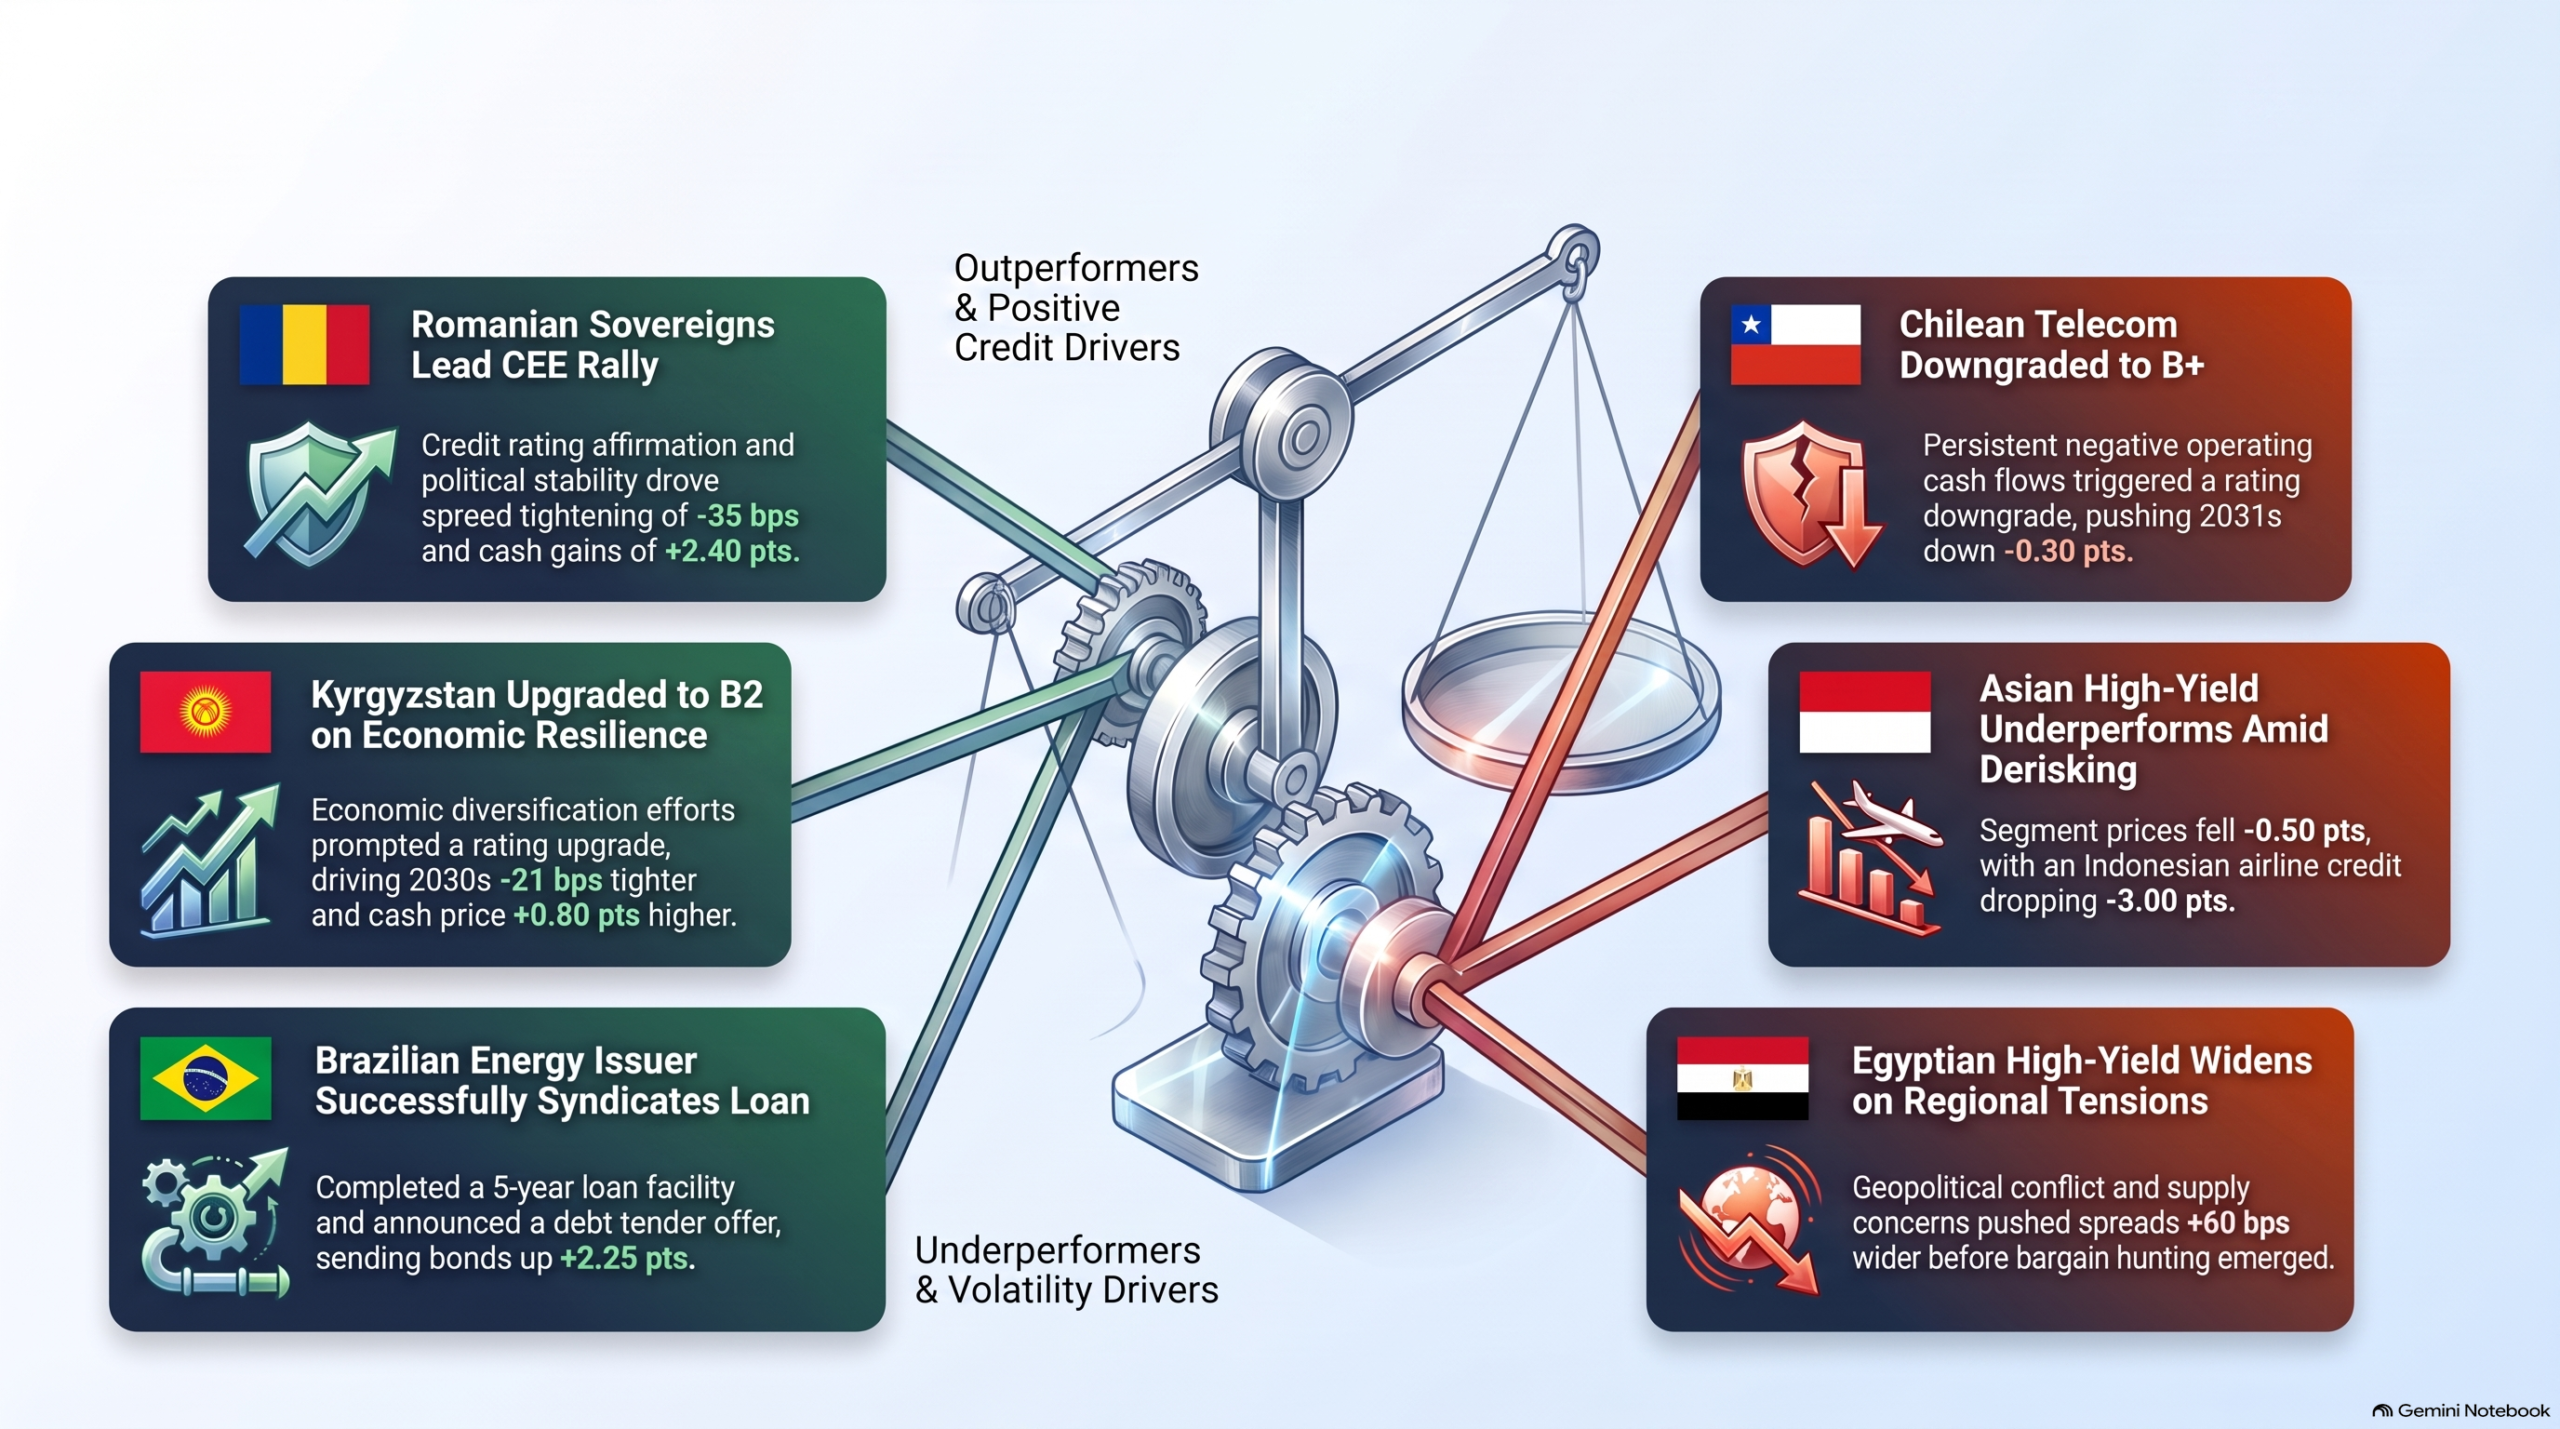
Weekly Snapshot: Key Drivers & Regional Flows
Global EM Themes
Flows & Technicals
- EM credit flows improved toward week-end as outflows largely subsided despite developed market volatility, supporting selective risk-taking across higher-yielding sovereign credits.
- Investment-grade Gulf credits remained resilient due to persistent institutional demand and limited primary market supply.
- Asia credit traded defensively, with investment-grade corporates generally 2-3bp wider and high-yield corporates declining 0.25-0.5pts on continued de-risking.
Macro & Economics
- Geopolitical risks remained a key market driver, particularly around the Middle East and Black Sea region, though risk assets generally stabilized during the week.
- Turkey’s September inflation data surprised positively at 29.7% YoY versus expectations of 30.3%, reinforcing confidence in the ongoing disinflation trend.
- Both Sri Lanka and Pakistan reached IMF staff-level agreements, supporting sentiment toward frontier sovereign credits.
Regional Developments
Middle East & Africa
- Egypt remained actively traded as investors balanced widening risk premiums driven by Middle East tensions against emerging value opportunities.
- Senegal drew significant investor focus amid discussions with creditors and the IMF regarding its restructuring framework and debt treatment.
- Cameroon successfully reopened its 2033 Eurobond with a US$300 million tap at a 10.8% yield, while Côte d’Ivoire and Kenya reported supportive fiscal developments.
Eastern Europe (CEE)
- Romanian sovereign bonds outperformed regional peers, tightening 15-35bp and gaining 1.8-2.4pts after rating affirmation and constructive political developments surrounding government formation.
- Ukraine sovereign bonds rebounded strongly, rising 1.8-2.9pts following additional European military and energy-sector support commitments.
- Kyrgyzstan benefited from a sovereign rating upgrade and saw its 2030 bonds tighten 21bp WoW while gaining 0.8pts in price.
- Turkey’s sovereign curve tightened 10-15bp WoW following the stronger-than-expected inflation print.
Latin America
- Brazil was among the strongest performers, with sovereign spreads tightening 15-22bp and 5-year CDS improving 22bp following the first round of presidential elections.
- Argentina continued to attract investor inflows, with sovereign CDS tightening significantly as broader regional demand remained supportive.
- Ecuador rebounded after authorities ruled out electricity blackouts during the peak drought period, supporting a recovery of 0.25-1.13pts across the curve.
- Transportation and industrial credits were mixed, with several aviation issuers outperforming while selected telecom and airline credits lagged despite corporate developments.
Asia
- Asia investment-grade corporates widened 2-3bp, with China technology and telecom names pressured by expectations of sizeable upcoming issuance.
- Regional investment-grade sovereigns outperformed corporates, with Indonesia and the Philippines tightening 1-3bp during the week.
- Pakistan underperformed Sri Lanka despite both receiving IMF support, while Laos delivered strong secondary-market performance after its new sovereign issuance.
- High-yield corporate sentiment remained weak, with transportation, gaming and property names declining amid risk reduction, although selected industrial issuers posted notable gains.
- A major Hong Kong property liability management exercise supported long-dated bonds, while perpetual securities lagged the broader capital structure.
Primary Markets
- Laos issued US$500 million of 5.5-year sovereign notes at a 9.625% yield, attracting a final orderbook of approximately US$1.45 billion with participation from EMEA, US and Asian investors.
- The new Laos issuance traded as high as 102.25 before settling around 101.5, representing a gain of roughly 1.5pts from reoffer levels.
- Several corporate refinancing, tender and liability management exercises across Asia and Latin America remained important drivers of secondary-market performance during the week.
GEMBRIDGE CAPITAL
www.gembridgecapital.com
www.gembridgecapital.com
DISCLAIMER
This document is strictly confidential and is being provided to you for informational purposes only. It does not constitute an offer to sell or a solicitation of an offer to buy any securities or financial instruments. The information contained herein has been obtained from sources believed to be reliable but is not guaranteed as to accuracy or completeness. Opinions and estimates constitute our judgment as of the date of this material and are subject to change without notice.
AI Generation Notice: Portions of this content may have been generated or assisted by Artificial Intelligence (AI) technologies. Users should independently verify critical data points. Past performance is not indicative of future results.
© 2026 Gembridge Capital. All rights reserved.